

The true cost of owning a car: build a realistic monthly budget
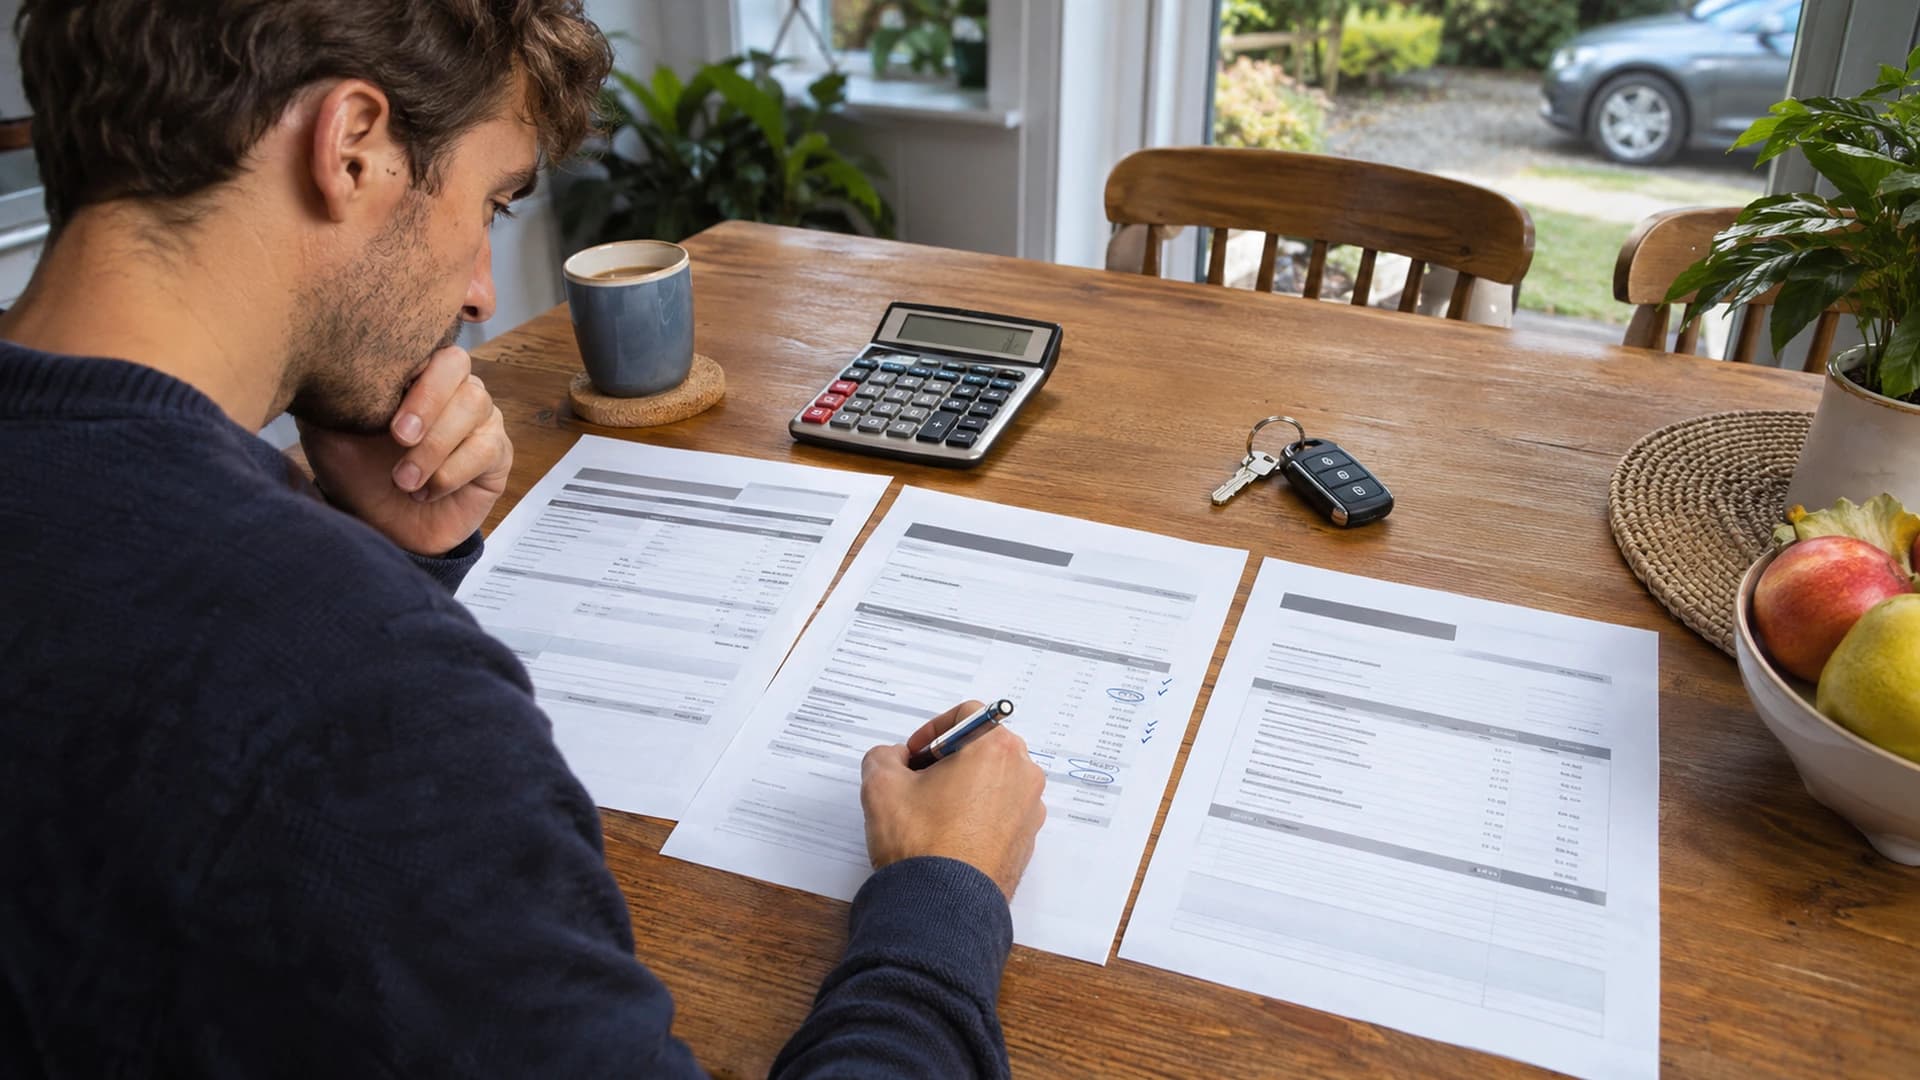
The instalment is only one part of a car's cost. Fuel or electricity, insurance, servicing and tyres continue after the excitement of collection, while larger expenses may arrive only once or twice a year. A useful ownership budget converts those irregular costs into a monthly amount and leaves room for surprises.
You do not need an elaborate spreadsheet to begin. Use a recent statement, a few quotations and the vehicle manufacturer's service information. The aim is to compare realistic scenarios, not to predict every repair with certainty.
Separate the purchase from the running costs
If you are financing the vehicle, ask for a written quotation showing the cash price, deposit, interest rate, fees, term, total repayment and any balloon payment. Check whether the interest rate can change and how a change affects your instalment. A balloon can reduce the monthly amount while leaving a substantial sum due at the end.
If you buy for cash, the instalment disappears but ownership costs do not. Consider how much of your savings will remain for an emergency, and remember that the money committed to the car cannot be used elsewhere. Avoid comparing a financed car's instalment with a cash car as if the latter were free to own.
For a fair comparison, list each vehicle's purchase or finance cost separately from its expected monthly running costs. Keep the assumptions visible so that you can change the distance, fuel price or insurance quote without losing track of the result.
Estimate the energy you will use
For a petrol or diesel car, estimate monthly kilometres and multiply by realistic consumption per 100 km, then by the price per litre. For example, 1,000 km at 7 litres per 100 km uses 70 litres. At an illustrative R24 per litre, that is R1,680. These are example figures, not a current fuel price or a promise of the car's actual consumption.
For an electric vehicle, apply the same idea using kWh per 100 km and the electricity price per kWh. Allow for charging losses and check whether you will use more expensive public charging for some trips. Real consumption varies with the route, traffic, speed, temperature and driving style, so test a higher-use scenario as well as your usual one.
Get an insurance quote for the exact car
Premiums depend on the vehicle, driver, location, use and cover selected. Ask for quotes using accurate details, then compare the insured value, excess, exclusions, security requirements and any tracking requirements. The cheapest monthly premium may come with a higher amount payable when you claim.
Check whether your policy covers financed accessories and what happens if the settlement amount exceeds the insured payout after a total loss. Ask your insurer or adviser to explain the options and exclusions. Review the policy when your circumstances change rather than assuming the original cover remains suitable forever.
Turn servicing and tyres into monthly amounts
Find the manufacturer's service intervals by time and distance. A car driven infrequently may still need a time-based service. Request a written estimate from an appropriate workshop and check what is included, such as fluids, filters and labour. Prices can change, so refresh the estimate periodically.
A service plan, maintenance plan and warranty are different products. Read their terms: the services, wear items, repair failures and exclusions covered can vary. Check the duration, distance limits, transfer rules and any required service conditions. Do not assume a plan pays for tyres or every repair.
Divide expected annual or periodic costs into monthly savings. If a set of tyres is estimated at R8,000 and you expect to replace it after 40 months, setting aside R200 a month provides a simple starting point. Actual life and prices vary; inspect tyres regularly and replace them when required, even if the budget has not reached its target.
Include the easy-to-forget costs
Add licence renewal, parking, tolls, washing, roadside assistance and any subscription or tracking fees relevant to your situation. If you commute, estimate tolls using your actual route and frequency. If you work from home some days, use your expected pattern rather than assuming the same trip every weekday.
Set aside a separate repair reserve, particularly for an older vehicle or one approaching the end of its warranty. A reserve is not a guarantee against a major failure, but it can reduce the shock of a battery, brake or suspension repair. Obtain model-specific estimates where you can rather than using another owner's costs as a promise.
Compare scenarios before committing
Add the monthly equivalents together. Then test what happens if fuel rises, the insurance premium increases, the car needs tyres earlier than expected or your financed instalment changes. Consider how long you intend to keep the car and what the remaining finance balance could be if you sell earlier.
Depreciation matters too: a car's future sale value is uncertain and varies with condition, mileage, market demand and history. Treat a predicted resale value as an estimate, not guaranteed money. Keeping service records and maintaining the vehicle can help a future buyer assess it, although neither guarantees a particular price.
The affordable car is the one you can maintain and insure as well as purchase. A realistic budget makes that decision clearer before the monthly costs become commitments.
Comments
Newest firstLoading comments…